December you is tired. December you is standing in a store on the 22nd, buying a $60 candle set for someone you barely like, putting it on a credit card, and thinking “I’ll deal with this in January.”
January you deals with it until March. And you’re not alone — 17% of shoppers are still carrying debt from last Christmas, according to the Intuit QuickBooks Holiday Shopping Report from September 2026. Nearly one in five lower-income shoppers expects to cut back on groceries or utilities just to afford Christmas this year.
Here’s the truth nobody mentions: the Christmas budget problem isn’t a December problem. It’s an October problem. By December, the money is already decided — you’re just choosing which card to put it on. The people who get through the holidays without debt made one calm decision back in October, when nobody was panicking.
This is that decision. Here’s the whole plan.
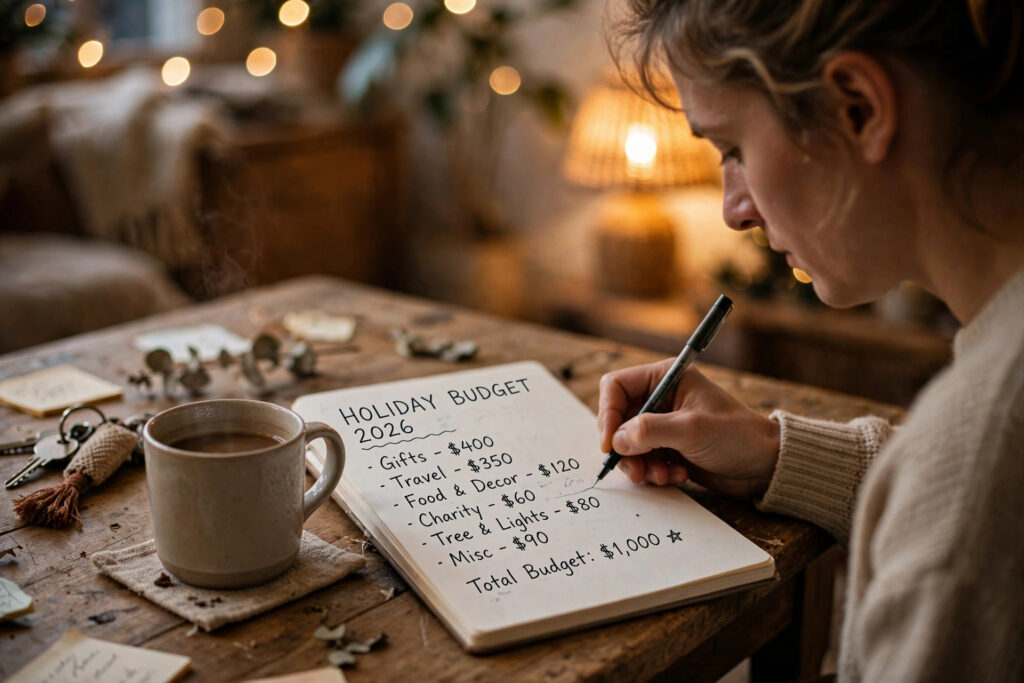
Why October Is the Real Start of Christmas
Think about how Christmas spending actually works. You don’t overspend because you’re bad with money. You overspend because December gives you about three weeks to make fifty spending decisions while you’re exhausted, emotional, and surrounded by ads telling you that love costs $129.99.
October you is a different person. October you is calm. October you can look at a number on paper and think clearly about it.
There’s a practical side too. Starting now means the cost gets spread out. A $600 Christmas budget hurts a lot less as $75 a week for eight weeks than as one brutal $600 crater in your December paycheck. Same money. Completely different feeling.
And honestly? Prices only go one direction from here. The stuff on your list in October is the cheapest it’ll be until next January. Waiting doesn’t save money — it just compresses the pain.
So if you want to know how to budget for Christmas without going into debt, the answer starts with timing: start now, while your brain still works.
Step 1 — Pick Your Total Number
Every Christmas budget plan starts with one number: the total. Not per person. Not per category. One total number for the whole holiday. Everything else flows from it.
Here’s a rule that actually works: spend 1 to 1.5% of your annual income on Christmas. That’s it.
Make $50,000 a year? Your Christmas number is $500 to $750. Make $35,000? It’s $350 to $525. Make $80,000? It’s $800 to $1,200.
Is this a perfect formula? No. But it’s honest, and it scales with your real life instead of some influencer’s gift guide. The people who get into trouble are the ones who spend like they make $80,000 when they make $40,000 — because nobody ever gave them a number to aim at.
Now break it down per person. Take your total and divide it by the number of people you’re buying for. If your number is $600 and you’re buying for 8 people, that’s $75 each. Write the names down. Write the amounts next to them. This is the part most people skip, and it’s the part that matters most — because “I’ll figure it out” is how $75 becomes $140.
Be brutally honest here. If money is tight this year, a smaller Christmas given with a clear head beats a big Christmas paid off until April. Nobody you’re buying for wants you in debt over their gift. And if they do — that’s useful information too.
Step 2 — Divide by Paychecks Left
This is the step that turns a wish into a plan. Take your total number and divide it by the number of paychecks you have left before Christmas.
Let’s do it with real numbers. Say your total is $600. Today is early October. If you get paid biweekly, you have about 5 paychecks left before Christmas. $600 divided by 5 is $120 per paycheck.
That’s the whole math. $120 per paycheck, set aside, and Christmas is fully funded by December 20th.
If you get paid monthly, it’s even simpler: $600 over roughly 2.5 months is $240 a month. If weekly, about $75 a week.
Here’s why this works when “just save for Christmas” doesn’t: it’s automatic and it’s specific. “Save for Christmas” is a vibe. “$120 every paycheck into the Christmas account” is a plan. Vague intentions die in week two. Specific numbers survive.
And here’s the part that makes it painless — you’re not finding $600 in December. You’re finding $120 now, when nothing is urgent and your budget still has room to breathe.
Step 3 — Open a Christmas Sinking Fund
A Christmas sinking fund is just a separate place where Christmas money sits until you need it. That’s all a sinking fund is: money you set aside a little at a time for a big expense you know is coming. Car insurance, vacations, and yes — Christmas.
Why separate? Because money in your checking account is already spent. You know this. Everyone knows this. The $120 that’s “for Christmas” but sitting in your main account becomes DoorDash by Thursday. A separate account — even just a free savings account at your current bank, or a separate envelope if you do cash — makes the money invisible to your daily spending brain.
Here’s how to set it up:
- Open the account. A free online savings account works. So does a second checking account. It takes ten minutes. Name it “Christmas 2026” so you see the label every time.
- Set up the auto-transfer. The day after each payday, your $120 (or whatever your number is) moves automatically. Not “when I remember.” Automatically. The transfer happening without your involvement is the entire strategy.
- Don’t touch it until December. This account is not an emergency fund. It’s not “I’ll borrow from it and put it back.” It sits there, growing quietly, until it’s time to buy gifts.
If your bank lets you create multiple savings buckets or vaults, even better — but don’t overthink the tool. The account is just a container. The auto-transfer is the plan.
By mid-December, you’ll open that account and find your full Christmas budget sitting there, already saved, and you’ll feel something most people never feel during the holidays: calm.
What Counts in a Christmas Budget (The Forgotten Costs)
Here’s where Christmas budgets die: people budget for gifts and forget everything else. Then the “everything else” shows up in January on a credit card statement.
Your real holiday budget 2026 needs all of this:
- Gifts — the obvious one, with per-person amounts from Step 1
- Travel — gas, flights, hotels, the “we’ll just drive” that costs $180 in gas and food
- Food — the big Christmas dinner groceries, baking supplies, the dish you’re bringing to someone else’s party
- Decor — new lights because half the strand died, the wreath, wrapping paper, tape, gift bags
- Shipping — mailing gifts to family far away; this alone surprises people every year
- Events — work party outfit, school concert tickets, the charity thing you can’t say no to
- Tips and extras — the mail carrier, the babysitter’s holiday bonus, the unexpected “we should get them something”
Add it all up honestly. Most people find the non-gift costs are 30 to 40% of their total holiday spending. If your gift number is $400 but your real total is $650, you need to know that in October — not discover it on December 26th.
Put every category in your total from Step 1. If the total gets too big, trim the gift list — not the budget. The budget is the truth. The gift list is negotiable.
How to Stick to It When December Gets Loud
Having the money saved is half the battle. The other half is not blowing past your number when December starts screaming at you.
Shop with the list, not the feeling. You wrote per-person amounts in October. Those amounts were decided by calm, rational you. December you is not qualified to revise them. When you’re tempted to upgrade someone’s gift, remember: October you already thought about this person and picked a number. Trust October you.
Set a “done” date. Pick December 18th or so as your shopping deadline. Everything bought by then. After that, you’re done — no “one more thing” trips. Most overspending happens in those last panicked days when the deadline pressure makes every gift feel urgent.
Unfollow the ads. December is an advertising ambush. Mute the influencers doing gift guides. Unsubscribe from the sale emails for one month. You can’t want what you don’t see, and your budget will thank you.
Have a script for the pressure. Someone will suggest the expensive group gift exchange. Someone will say “let’s all go in on something big for Mom.” Have your line ready: “I’m keeping it simple this year — I’m in for $X.” No apology, no explanation. People respect a clear number way more than a vague “money’s tight.”
Track as you spend. Keep a running total on your phone. Every purchase gets subtracted from the Christmas account balance in your notes. Watching the number go down in real time is the single best overspending killer — it makes the invisible visible.
If You’re Already Behind
Maybe you’re reading this in late October or November and thinking “great plan, but I’m already behind.” No shame. Here’s the scaled-back version:
Cut the number, not the plan. Run the same three steps with a smaller total. A $300 Christmas fully funded beats a $600 Christmas half-funded and half-credit-carded. The plan works at any size.
Shrink the gift list first. Adults in the family getting individual gifts? Suggest a Secret Santa or a spending cap — most families are relieved when someone says it out loud. Kids’ gifts stay; the $40 candle for your coworker goes.
Go homemade where it counts. Baked goods, a handwritten letter with a small gift, an offer of your time — these land harder than expensive generic gifts anyway. The best gift most adults get all year is someone actually thinking about them.
Start the sinking fund anyway. Even if you can only put away $50 per paycheck, that’s $50 you won’t put on a credit card. And here’s the real win: when January comes, keep the auto-transfer running. By next October, you’ll have a full year of Christmas savings. Future you will be so glad.
The worst move is doing nothing because you can’t do it perfectly. A half-funded plan beats no plan every time.
Frequently Asked Questions
How much should I spend on Christmas?
A solid rule: 1 to 1.5% of your annual income. On a $50,000 salary, that’s $500 to $750 for everything — gifts, travel, food, decor, all of it. Adjust for your real situation, but having a number matters more than having the perfect number.
What is a Christmas sinking fund?
It’s a separate savings account (or envelope) where you put a fixed amount from each paycheck between now and December, specifically for holiday spending. By Christmas, the full budget is already saved — no scrambling, no credit cards.
Is it too late to start a Christmas budget?
No. Starting late with a smaller number beats not starting at all. Run the same three steps — pick a total, divide by paychecks left, auto-transfer what you can. Even partial funding means less January debt.
Should I use a credit card for Christmas and pay it off?
Only if the money is already sitting in your sinking fund and you’re using the card for points or convenience — then pay it off immediately. If “pay it off” means “hopefully by spring,” that’s not a strategy, that’s debt with extra steps.
The One Decision
Here’s everything in one sentence: pick your total Christmas number today, divide it by your remaining paychecks, and auto-transfer that amount into a separate account after every payday.
That’s the whole plan. One calm October decision, and December becomes something it almost never is: affordable.
Your future self — the one relaxing on December 23rd instead of panic-shopping — is counting on you to make it now.
Pingback: Debt Snowball vs Avalanche: Pay Off Debt Before Holidays
Pingback: High-Yield Savings Account for Beginners: Up to 5% in 2026
Pingback: Sinking Funds for Beginners: End 'Surprise' Bills (2026)
Pingback: How to Budget for Halloween 2026: Beat the $210 Average
Pingback: Store Credit Cards: Why '20% Off Today' Costs You More (2026)
Pingback: Winter Heating Bills 2026–27: Oil Homes Pay 21% More
Pingback: Black Friday Budget 2026: The October Plan That Stops the Sale From Spending You
Pingback: Holiday Travel Budget 2026: Flights Are at a 10-Year High — Here Is How to Still Save $250 a Ticket
Pingback: Holiday Side Hustles 2026: Amazon Is Hiring 300,000 People at $20 an Hour — Apply This Week, Not in December - Luxiro
Pingback: Christmas Gifts Under $25: The Cap System That Keeps Everyone on Your List - Luxiro
Pingback: The November Money Checklist: 7 Moves to Make Before December Eats Your Budget - Luxiro