The Biweekly Budget: How to Budget When You Get Paid Every Two Weeks
Your budget is not failing because you are bad with money. It is failing because it was built for a calendar you do not live on.
Most budgeting advice assumes you get paid once a month, or twice a month on neat dates like the 1st and the 15th. But the most common pay schedule in America is every two weeks. According to the US Bureau of Labor Statistics, 43.0% of private employers pay biweekly — more than weekly (27.0%), semimonthly (19.8%) or monthly (10.3%). If that is you, you get 26 paychecks a year, your paydays drift across different dates every month, and your rent is due on the same date every month whether your paycheck shows up before it or after it.
That mismatch is the whole problem. A monthly budget pasted onto a biweekly paycheck will feel broken twice a year, tight once a month, and mysteriously flush the rest of the time — and you will blame yourself for a maths problem that was never yours.
This guide rebuilds the budget around the paycheck you actually get: how to turn 26 checks into a monthly number, how to split your bills between Check 1 and Check 2, and what to do with the two famous three-paycheck months so they stop evaporating.
Why the Standard Monthly Budget Breaks on a Biweekly Paycheck
Three facts collide here:
Your income arrives 26 times a year. Your bills arrive 12 times a year. Two paychecks a month, times twelve months, is 24 paychecks. You get 26. Those two extra checks are real money — a full month’s pay across the year — but because they land inside “normal” months, most people spend them like a bonus and never feel the benefit.
Your paydays move. Paid every other Friday, your checks land on the 1st and 15th one month, the 10th and 24th the next. Any bill with a fixed due date will sometimes fall before payday and sometimes after. A budget that works “as long as rent comes after the second check” is a budget that works about half the year.
The stakes of getting this wrong are not small. PYMNTS Intelligence found that about two in three US adults — roughly 67%, an estimated 180 million people — live paycheck to paycheck in 2026, including about half of consumers earning $100,000 a year or more. Read that second part again. At six figures, the problem is rarely the size of the paycheck. It is the timing of the paycheck against the timing of the bills. Timing is fixable. That is what this system does.
The Core Rule: Budget on Two Checks, Plan on Twenty-Six
Everything in a biweekly budget hangs on one decision:
Your monthly budget is built on exactly two paychecks. Never two and a bit. Never the average.
Here is the maths, using a clean example. Say your take-home pay is $2,000 every two weeks:
- Annual take-home: $2,000 × 26 = $52,000
- True monthly average: $52,000 ÷ 12 = $4,333
- Your budget base: 2 × $2,000 = $4,000 a month
That $333 gap between the monthly average and your two-check budget is not an error. It is the entire system. You live on $4,000 a month, every month, no exceptions — and the extra $4,000 a year (the two third paychecks) gets assigned a job in advance, in Step 3 below. People who budget on the $4,333 average run short in ten months and float in two. People who budget on $4,000 run even in ten months and surge ahead in two. Same salary. Different rule.
If percentages help you, fine — run your two-check base through a simple split like the 50/30/20 rule: on a $4,000 base, that is $2,000 for needs, $1,200 for wants, $800 for savings and extra debt payments. The percentages are the easy part. The pay schedule is the part everyone skips.
Step 1: List Every Bill With Its Due Date, Not Just Its Amount
Get your bank statements from the last two months and write down every recurring bill with two facts attached: how much, and due on which date. Rent or mortgage, utilities, phone, internet, insurance, car payment, subscriptions, minimum card payments, childcare — all of it.
Most people have done the amounts half of this exercise. Almost nobody has done the dates half, and the dates half is the one that decides whether you bounce between paychecks. You are looking for one thing: which bills cluster together. If $1,900 of bills land in the first half of the month and $700 in the second half, no amount of willpower fixes that. You fix it in Step 2 by moving money, and in Step 5 by moving due dates.
Add the bills that do not show up monthly, too — car insurance every six months, annual subscriptions, registration, the lot. Divide each by the number of paychecks between now and its due date and give it a small line in every check. That is a sinking fund, and on a biweekly schedule it matters more than anywhere else, because an annual bill landing on the wrong Friday can wreck a month that was otherwise fine.
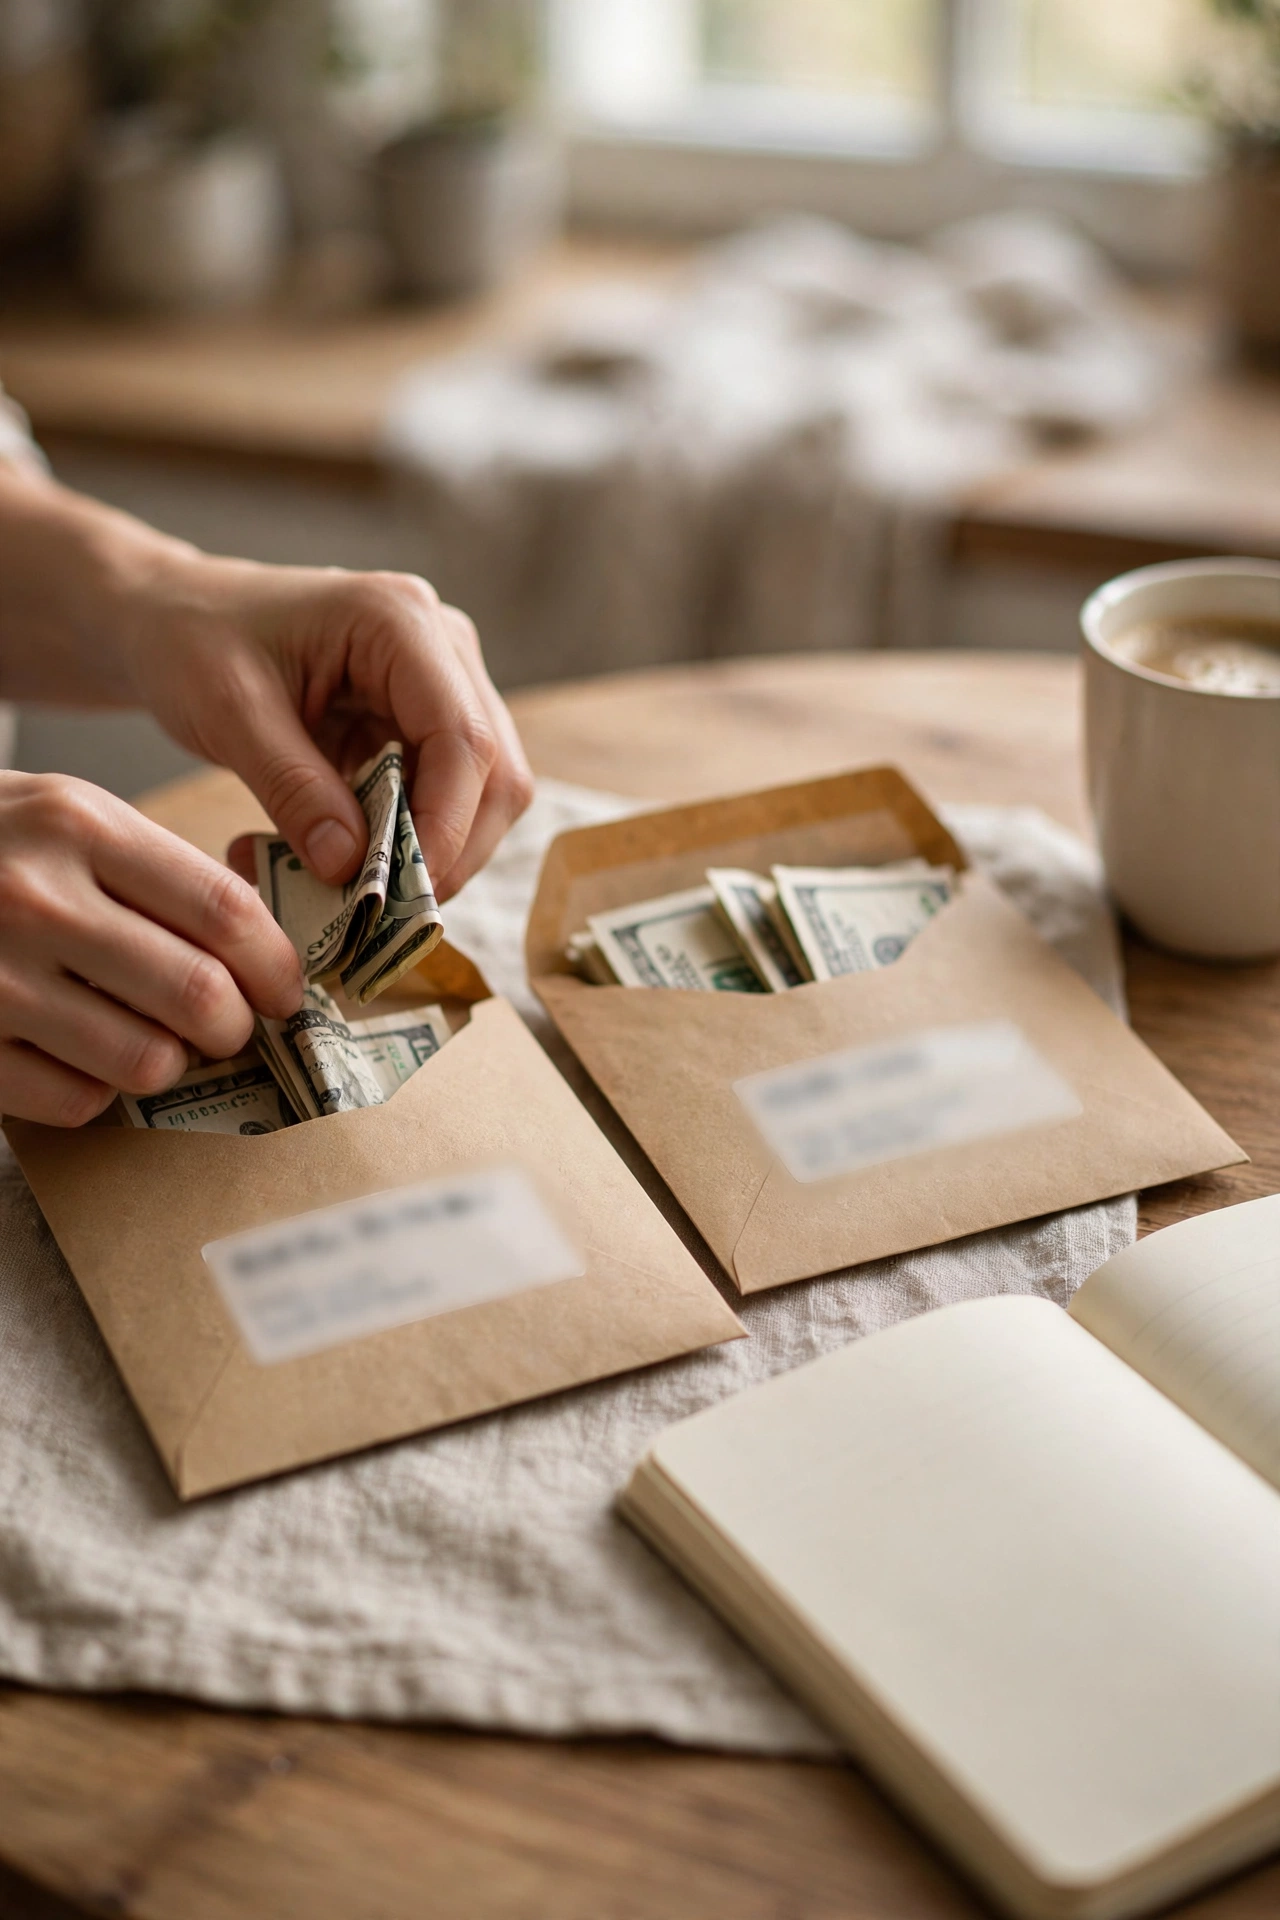
Step 2: Split Your Bills Between Check 1 and Check 2
Now assign every bill to the paycheck that will pay it. The goal is balance: each check carries roughly half your monthly bills, and each bill is paid by the check that arrives just before its due date.
With our $2,000 example check, a workable split looks like this:
Check 1 (first Friday):
- Half the rent: $750 set aside (rent is paid whole, from both halves — see below)
- Car payment: $340
- Phone: $85
- Subscriptions and small bills: $60
- Groceries and spending money until Check 2: $400
- Sinking funds and savings transfer: $200
Check 2 (second Friday):
- Second half of the rent: $750 set aside
- Utilities: $180
- Insurance: $150
- Minimum card payments: $120
- Groceries and spending money until Check 1: $400
- Sinking funds and savings transfer: $200
Notice the rent trick, because rent is where biweekly budgets go to die. If your rent is $1,500 and it is due on the 1st, and your first October check lands on the 9th, you are late — not irresponsible, just misaligned. The fix is to fund rent in halves: $750 out of every check goes into a bills account and stays there, so the full $1,500 is sitting ready on the 1st no matter where your paydays fall that month. This takes one uncomfortable month to establish. After that, rent stops being a crisis with a date on it.
Use a separate bills account if your bank allows it. One account where paychecks land and bills leave, one account for daily spending. When the bills money is physically somewhere else, you stop doing mental arithmetic every time you check your balance — and mental arithmetic at the grocery store is where budgets actually die.
Step 3: Give the Two Three-Paycheck Months a Job in Advance
Twice a year, a third Friday payday lands inside one calendar month. In a normal 26-payday year it happens exactly twice. Those two checks are your $4,000-a-year gap from the core rule — a full extra month of pay — and they are the most wasted money in most households, because they arrive looking like a windfall.
Decide their job now, while no sale is talking to you:
- Third check #1: Kill a debt or fund a known big cost. Extra principal on your highest-interest balance, or the car insurance you know is coming.
- Third check #2: Build the buffer in Step 4, or fund a sinking fund goal outright.
What a third check is not: catch-up money for overspending, a reason to upgrade something, or proof the budget can stretch this month. If your two-check budget is honest, the third check is pure progress money — it is the only pay you will ever get that has no bills attached to it. Spending it on lifestyle is choosing, twice a year, to stay exactly where you are. That sounds harsh. It is also the entire reason some people on your exact salary get ahead and some do not.
Write down, right now, which months your three-paycheck months fall in this year. Count forward on a calendar from your last payday, every other week, and mark them. Ten minutes. Those two marked months are your financial year now.
Step 4: Build a One-Paycheck Buffer and End the Timing Problem Forever
Every fix above manages the mismatch between your paydays and your bills. The buffer deletes it.
A one-paycheck buffer means you are always spending last month’s money: the check that lands Friday covers bills starting two weeks from now, not bills due Monday. Once you have it, due dates stop mattering. Rent on the 1st, payday on the 9th — who cares? The money was already there.
Build it in this order:
- Starter cushion: $500. Park it in the bills account and pretend it is not yours. This absorbs the small misalignments — the utility bill that lands two days early.
- Half a paycheck. On our example, $1,000 total cushion. Now a bad-timing week is boring instead of expensive.
- A full paycheck. $2,000 in the example, which for most biweekly workers is around the size of a proper starter emergency fund anyway. At this point you are budgeting a month ahead and the calendar can do whatever it wants.
Fund it from the third checks first, then $50 to $100 a check in the normal months. It is slow for the first two months and then it is just there, quietly removing the most stressful part of your financial life. Of everything in this guide, this is the step people thank themselves for a year later.
Step 5: Move the Due Dates That Fight Your Paydays
Here is a move nobody tells beginners: most due dates are negotiable. Credit card issuers, phone companies, utilities and insurers will often shift your billing date if you call and ask — usually once, politely, in about five minutes.
Use it to finish the balancing job from Step 2. If three big bills all land in Check 1’s territory, ask one provider to move your due date two weeks later and let Check 2 carry it. Aim for a month where no single paycheck is asked to cover more than about half your monthly bills plus its share of rent.
Do not move a due date until you know your real payday pattern — moving dates to fix last month’s problem can create next month’s, because your Fridays drift. Move them once, toward balance, then leave them alone.
The Biweekly Mistakes That Keep Smart People Broke
Budgeting on the monthly average. Covered above, worth repeating: $4,333 thinking on a $4,000 life means ten short months a year. Budget on two checks.
Confusing biweekly with semimonthly. They are not the same. Semimonthly is 24 checks a year, always on the same two dates. Biweekly is 26 checks, drifting dates, two three-check months. Plans built for one break on the other — check your pay stub if you are not sure which one you are.
Treating weekly spending money as monthly money. Give yourself spending money per check, not per month. $400 per check is a clear, checkable limit for two weeks. $800 a month gets spent in the first ten days by perfectly normal humans.
Forgetting the bills that skip months. The annual and twice-a-year bills are invisible in a normal month and catastrophic in theirs. The per-check sinking fund line — even $25 a check — is what separates “surprise $600 insurance bill” from “already handled.”
Letting the good fortnight fool you. Some pay periods contain no big bills at all, and the balance looks healthy, and that is precisely when the damage happens. The balance is not your money’s mood. Check the assignment list from Step 2 before you trust it.
FAQ
How do I calculate my monthly budget if I am paid biweekly? Multiply one take-home paycheck by 26 and divide by 12 for your true monthly average — but budget below it. Set your monthly spending plan at two paychecks exactly. On a $2,000 check, the average is $4,333 but the budget base is $4,000, and the difference is funded by the two three-paycheck months, which you assign in advance to debt, savings or your buffer.
What should I do with a three-paycheck month? Treat it as already spent — on paper, before it arrives. Because your monthly budget runs on two checks, the third check has no bills attached. Send it where it does the most permanent good: highest-interest debt, your one-paycheck buffer, or a sinking fund for a known big cost. What you do not do is raise your spending for that month, because the month after it is a two-check month again.
How do I pay rent on time when my payday moves? Fund rent in halves. Set aside half the rent from every paycheck into a bills account, so the full amount is waiting on the due date no matter where your Fridays land. It takes one tight month to set up; after that the alignment problem is gone, and a one-paycheck buffer (Step 4) removes it permanently.
Is the biweekly budget different if I am paid weekly? The same logic applies with the numbers changed: budget on four weekly checks a month ($4,000 on a $1,000 weekly check), and the four months a year with a fifth payday become your progress money, just like three-paycheck months for biweekly workers. Weekly pay makes the buffer even more valuable, because five different weekly due-date collisions can happen in a single month.
You do not need a new app, a new salary or a new personality to fix this. You need your budget to run on the schedule your money actually arrives on: two checks a month as the base, every bill assigned to a check, the rent funded in halves, the two extra checks a year working instead of evaporating, and a one-paycheck buffer slowly making the calendar irrelevant.
Start with Step 1 today — the list with the due dates. That one piece of paper shows most biweekly workers, for the first time, that they were never bad at budgeting. They were just budgeting in the wrong month shape.
Pingback: Savings Challenges Ranked: Which Viral Challenge Actually Puts Money in Your Account?
Pingback: Zero-Based Budgeting for Beginners - Luxiro